
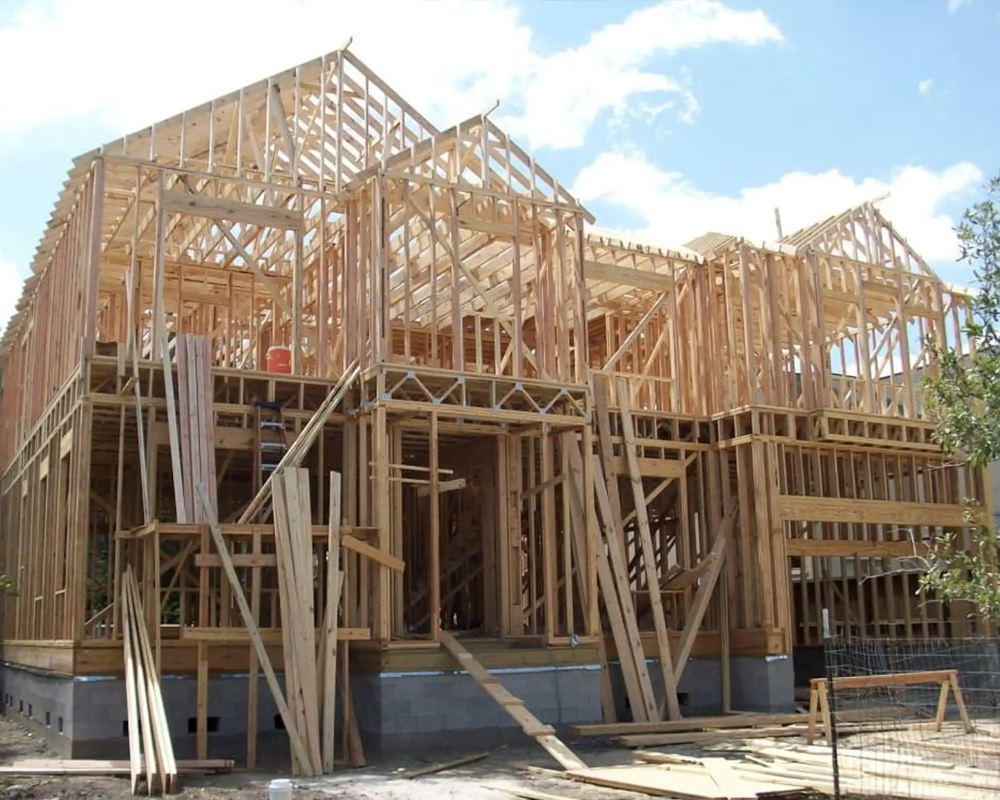
A construction home loan is a short-term financing solution designed specifically to fund the building or renovation of a residential property. Unlike a traditional mortgage that provides a lump sum for an already-built home, this type of loan releases funds in stages as the construction progresses. The money covers materials, contractor labor, and related expenses—ensuring work continues smoothly without financial roadblocks.
Once the project is complete, the construction loan can either be refinanced into a permanent mortgage or converted into a standard long-term home loan. Borrowers will need detailed architectural plans, a licensed builder, and proper documentation for approval. While every lender has unique requirements, construction loans give homeowners the flexibility to bring their vision to life while keeping costs structured and manageable.
Combines construction funding and a permanent mortgage into one package, with only one application and one set of closing costs.
Covers only the building phase; once complete, borrowers refinance into a traditional mortgage.
Rolls renovation or remodeling costs into your mortgage, perfect for fixer-uppers or home improvements.
Designed for borrowers acting as their own contractor, saving on labor costs while overseeing the project.
We strive to offer competitive and transparent pricing on all our mortgage and loan programs. Our goal is to help you secure the best possible financing with no hidden costs and exceptional service every step of the way. We’re confident in the value we provide—check out our Best Price Guarantee to see how we ensure you get the most affordable rates and unbeatable service tailored to your needs.
One Loan, Two Phases – Simplify financing with combined construction and permanent mortgage options.
Fixed-Rate Protection – Lock in your rate during the construction period to avoid market fluctuations.
Flexibility in Timeline – Borrowers typically have up to a year to complete the project, giving room for delays or adjustments.
Customization – Tailor your financing to match your goals, whether it’s a new build, remodel, or acting as your own builder.
Construction home loans are designed to offer both convenience and security, ensuring you can focus on building without worrying about funding interruptions.
Applying for a construction home loan involves more preparation than a traditional mortgage. Lenders carefully evaluate your financial background, including credit score, debt-to-income ratio, income stability, and overall financial readiness. Most lenders prefer a minimum credit score of around 680 and a debt-to-income ratio under 45%, though some programs exist for less-than-perfect credit.
Beyond financial qualifications, you’ll also need to present detailed architectural drawings, building permits, a construction timeline, and a budget breakdown covering labor, materials, and potential contingencies. Builders must be licensed, and lenders may require certifications or proof of experience. During the project, funds are released in stages, and inspections ensure each phase is completed before additional money is disbursed.
The application process can feel complex, but working with an experienced loan officer streamlines everything. From selecting the right loan type to preparing documentation and setting a realistic repayment plan, the right guidance ensures your project moves forward without unnecessary delays. With proper planning and support, securing financing for your dream home becomes a smooth, structured journey.
While construction loans offer flexibility and make building your dream home possible, it’s important to be aware of the costs and requirements. Interest rates are typically higher than traditional mortgages, and upfront fees such as origination costs, inspections, and closing fees can add up quickly. Since repayment often begins during construction, borrowers should budget carefully to manage both current living expenses and new loan payments.
Another important factor is preparation. Having a clear plan, realistic budget, and qualified builder improves both your chances of approval and the project’s success. Lenders want to see that you have the financial discipline and professional support to finish the build on time and within budget. By planning ahead and working closely with your loan officer, you can confidently move through the process and turn your vision into reality.
To apply for a home loan, you’ll need to provide proof of income, your credit history, and employment verification. Additionally, you’ll need to submit recent tax returns and details about your assets and liabilities. To apply for a home loan, you’ll need to provide proof of income, your credit history, and employment verification,
To apply for a home loan, you’ll need to provide proof of income, your credit history, and employment verification. Additionally, you’ll need to submit recent tax returns and details about your assets and liabilities. To apply for a home loan, you’ll need to provide proof of income, your credit history, and employment verification.
To apply for a home loan, you’ll need to provide proof of income, your credit history, and employment verification. Additionally, you’ll need to submit recent tax returns and details about your assets and liabilities. To apply for a home loan, you’ll need to provide proof of income, your credit history, and employment verification.
To apply for a home loan, you’ll need to provide proof of income, your credit history, and employment verification. Additionally, you’ll need to submit recent tax returns and details about your assets and liabilities. To apply for a home loan, you’ll need to provide proof of income, your credit history, and employment verification.
Take advantage of our client resources designed to make your homebuying journey easier and more informed. Browse through our website to learn more about our company, explore the wide range of loan programs we offer, and discover the right financing solutions for your unique needs.